What is the scope and industry significance of the Carcinoid Syndrome Management Market?
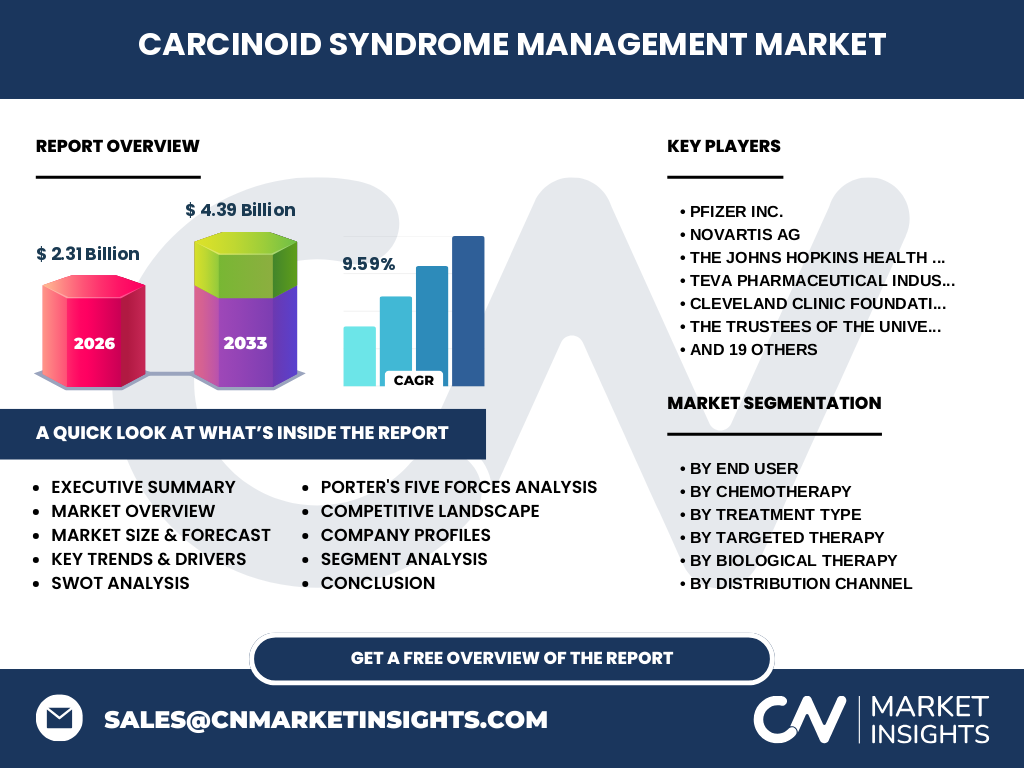
Our analysis indicates that the Carcinoid Syndrome Management Market addresses the complex neuroendocrine tumor complications, anchoring a baseline valuation of 2.31 Billion in 2026. This sector encompasses advanced therapeutics and surgical interventions regulated strictly by the FDA and EMA to control debilitating flushing and diarrhea.
Structural Growth Drivers and Restraints
The market is propelled by a rising neuroendocrine tumor incidence and expanded FDA approvals for Somatostatin Analogues like Octreotide and Lanreotide. However, our research highlights severe reimbursement hurdles in emerging regions and high supply chain costs for complex Lutetium 177 radiopharmaceuticals as primary market restraints.
Emerging Trends and Growth Patterns in Carcinoid Syndrome Management
The shift toward precision oncology is redefining therapeutic trajectories. Peptide Receptor Radionuclide Therapy (PRRT) and targeted treatments using Everolimus are gaining dominant traction. Providers are increasingly relying on specialized online pharmacies and direct-to-provider channels to streamline patient access for rare therapies.
How COVID-19 Impacted the Industry Recovery Trajectory
Pandemic-related elective surgery postponements initially suppressed demand for debulking and liver resections. Recovery accelerated sharply post-2021 as hospitals cleared surgical backlogs and regulatory bodies streamlined decentralized clinical trials, restoring steady momentum to the Carcinoid Syndrome Management Market industry trends.
Competitive Benchmarking and Market Concentration
The landscape features intense competition among major pharmaceutical innovators like Novartis AG, Pfizer Inc., and Ipsen Pharma. These industry leaders leverage aggressive pipeline expansions and strategic acquisitions in targeted therapies to maintain high market concentration and defend their proprietary biological therapy portfolios.
Executive Summary of Key Findings
Our comprehensive assessment projects the Carcinoid Syndrome Management Market market size to expand from 2.31 Billion in 2026 to 4.39 Billion by 2033 at a robust CAGR of 9.59%. Growth is heavily anchored by specialized oncology centers and advanced radiopharmaceutical adoption.
Long-Term Market Forecast from 2027 to 2033
Driven by accelerating clinical trial readouts and rising diagnostic rates, the sector is poised for exponential expansion. Our financial modeling confirms a steady trajectory reaching the 4.39 Billion valuation mark by 2033, translating to a consistent 9.59% CAGR driven by global oncology investments.
Segmentation Analysis Across Therapeutics and Delivery
The market diversifies across treatment types including Somatostatin Analogues, Chemotherapy, Targeted Therapy, and Radiopharmaceuticals. End-user segmentation spans hospitals, specialty clinics, and ambulatory surgical centers, while routes of administration cover injectable, oral, and intravenous pipelines designed for optimized patient compliance.
Regional Market Analysis and Geographic Distribution
North America dominates global consumption due to high diagnostic rates and favorable Medicare reimbursement policies. Meanwhile, Asia-Pacific emerges as the fastest-growing region, propelled by expanding healthcare infrastructure in urban centers and rising adoption across major hospital networks in India and regional hubs.
In-Depth Regional Review of Healthcare Infrastructure
U.S.-based institutions such as Mayo Clinic, Memorial Sloan Kettering Cancer Center, and The Johns Hopkins Health System Corporation set global benchmarks in clinical protocols. Conversely, European markets face stringent EMA pricing negotiations, favoring cost-effective generic chemotherapies like Streptozocin and Capecitabine.
Strategic Positioning of Leading Companies
Market pioneers like Teva Pharmaceutical Industries Ltd. focus on accessible chemotherapy formulations, whereas Novartis AG capitalizes on breakthrough radiopharmaceuticals like Lutetium 177 Therapy. Specialized networks like Cleveland Clinic Foundation and MD Anderson Cancer Center drive clinical validation through high-volume surgical resections.
Porter's Five Forces Analysis of Competitive Pressures
Bargaining power of buyers remains moderate due to strict insurance pre-authorization requirements. Supplier power is low for generic active pharmaceutical ingredients but high for proprietary radioisotopes. Threat of substitutes is mitigated by the specialized efficacy of targeted therapies and peptide receptor radionuclide treatments.
SWOT Analysis of the Industry Ecosystem
Core strengths include sophisticated diagnostic tools and robust targeted therapy pipelines. Key weaknesses involve high treatment costs and complex cold-chain logistics for radiopharmaceuticals. Opportunities lie in emerging biologics, while threats stem from strict regulatory compliance and potential generic patent challenges.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with chemical and radioactive raw material sourcing, advancing through strict FDA-regulated pharmaceutical manufacturing. Products flow via specialized distributors to hospital pharmacies and retail outlets, ultimately reaching oncology specialists administering treatments at leading medical centers.
Strategic Investment Insights and High-Potential Areas
Investors should prioritize companies developing next-generation radiopharmaceuticals and targeted tyrosine kinase inhibitors. High-potential opportunities exist in partnering with specialized ambulatory surgical centers and expanding clinical access across underserved Asia-Pacific markets to capture untapped patient pools.
Conclusion and Strategic Takeaways
The Carcinoid Syndrome Management Market represents a high-growth oncology segment backed by strong demographic fundamentals and therapeutic innovations. Sustained investments in precision medicine and targeted radiotherapies will define market leaders as the sector scales toward its 2033 projections.
Research Methodology and Data Triangulation
Our baseline estimates are rigorously triangulated by combining global trade registry data, primary stakeholder interviews with key oncology department heads, and secondary macroeconomic indicators from international health organizations, ensuring high-fidelity market size and CAGR validation.
Scope of the Report and Coverage Parameters
This report covers global revenue performance across 2026 baseline metrics through the 2027-2033 forecast period. Limitations include restricted transparency in specific localized emerging market pricing policies and proprietary clinical trial expenditure data from private research institutions.
Recent Developments and Strategic Industry Moves
Recent milestones feature accelerated FDA approvals for novel monoclonal antibody therapies and strategic institutional collaborations between Stanford Health Care and pharmaceutical developers. These partnerships aim to fast-track clinical trials for refractory neuroendocrine tumor cases and expand patient access channels.